Greater Phoenix · Maricopa County

Phoenix mortgage broker & loan officer

One city, many different housing markets.

County
Maricopa
Housing mix
Historic bungalows to high-rise condos
Common loans
Conventional · FHA · VA · Jumbo
Assumable inventory
Worth checking, neighborhood by neighborhood
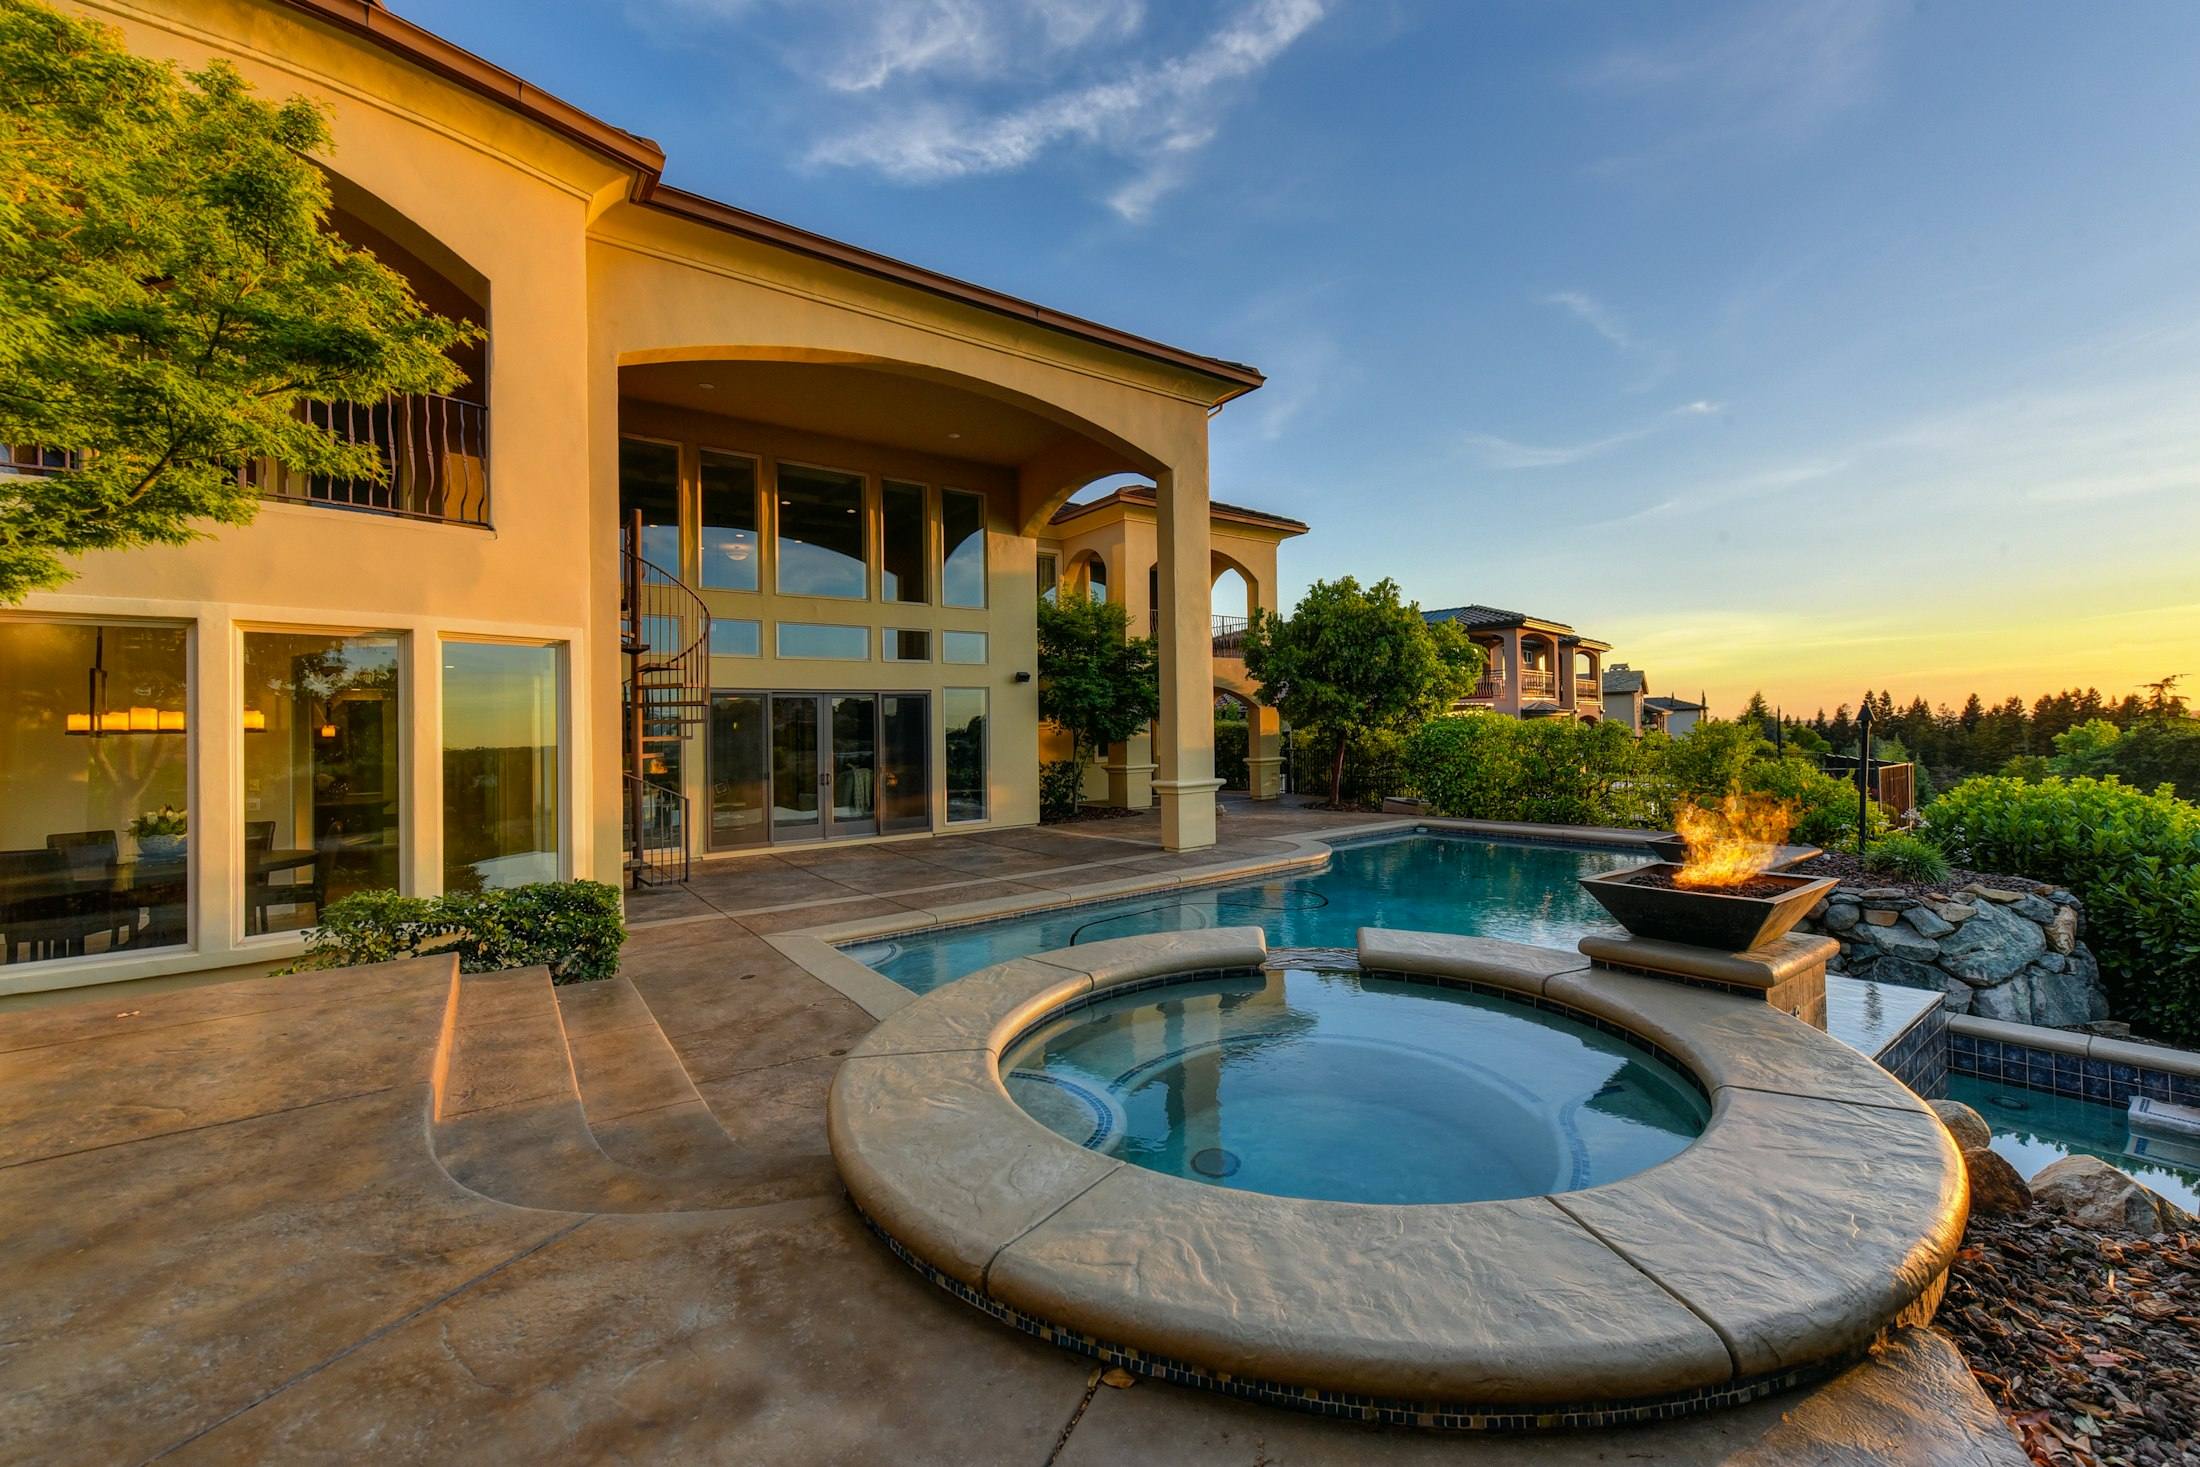
Southwest stucco home with a pool and spa at sunset in Phoenix

Buying in Phoenix

Phoenix is less a single market than a collection of very different ones, from 1920s bungalows in Willo to downtown high-rises and newer homes in Laveen and Desert Ridge. The right loan depends heavily on which part of Phoenix you are buying in. I help buyers match the financing to the house, the neighborhood and the long-term plan.

Local housing context

What shapes financing in Phoenix

01

Every price point in one city

Within a short drive you can go from entry-level condos and starter homes to Arcadia and Biltmore properties that push into jumbo territory. That range means almost every loan program has a natural place somewhere in Phoenix. Comparing options early keeps you from forcing one program onto the wrong property.
02

Older homes and property condition

Historic districts and mid-century neighborhoods have real charm, but appraisers on FHA and VA loans look closely at roofs, electrical, plumbing and safety items. Knowing what minimum property requirements may flag helps you negotiate repairs before they become a closing-week surprise. Conventional financing can sometimes be more forgiving on cosmetic condition.

03

Condos need project review too

Downtown, Midtown and Biltmore-area condos are popular with first-time buyers and downsizers alike. Lenders review the condo project itself, including budgets, owner-occupancy and litigation, and FHA or VA financing generally requires the project to meet program approval requirements. Checking the building early saves time.

Neighborhoods

Areas I often finance

Every neighborhood carries its own mix of property types, HOAs and price points, and each one changes the right loan structure.

  • Willo, Encanto-Palmcroft & Coronado

    Historic homes where inspection findings and appraisal conditions matter as much as the rate.

  • Arcadia & North Central

    Larger lots and remodeled or rebuilt homes that often call for conventional or jumbo financing.

  • Biltmore & Downtown condos

    Condo and high-rise living where the project review is part of the loan approval.

  • Ahwatukee

    Established neighborhoods along South Mountain with a mix of FHA, VA and conventional buyers.

  • Desert Ridge & North Phoenix

    Newer master-planned areas where loans from the low-rate years can make assumptions worth a look.

  • Laveen & South Mountain

    Newer construction and value pricing that often suits first-time buyers using FHA or VA.

Assumable mortgages · Phoenix

Could you take over a seller’s lower rate?

Assumable FHA and VA loans show up across Phoenix, often in homes bought or refinanced in 2019–2021. Each one is subject to servicer approval and buyer qualification, and the equity gap is usually the deciding factor.

FHA, VA and USDA loans may be assumable with servicer and agency approval. Buyers must qualify, and the equity gap between price and loan balance generally must be covered with cash or permitted secondary financing.

Local notes from Patrick

Start with the house, then pick the loan

In Phoenix I often meet buyers who already decided on a loan type before they found the house. That works fine in Laveen or Desert Ridge, but a 1930s home in Coronado or Willo may tell a different story once the appraiser walks through. I like to talk through the property type first so the financing fits what you are actually buying.

Condos and older homes

If you are looking downtown or in Midtown, send me the building name early. I can check whether the project is likely to work for the loan you want before you spend money on inspections. For older single-family homes, I would rather you know about a likely FHA or VA repair condition during negotiations than after.

Where assumptions fit

Assumable loans are scattered across Phoenix rather than concentrated in one place. When a listing mentions one, I compare the assumption against a new FHA or conventional loan side by side. My buying in Phoenix guide is a good next read.

FAQ

Phoenix mortgage questions

Can I use an FHA or VA loan on a historic home in Phoenix?

Often yes, as long as the home meets the program's property requirements for safety, soundness and security. Older roofs, wiring or plumbing can trigger repair conditions, so a good inspection and early conversation help.

Are downtown Phoenix condos harder to finance?

They can take a bit more work because the lender reviews the building as well as the buyer. Some projects are approved for FHA or VA and some are not, so I check that before you write an offer when possible.

Which Phoenix neighborhoods tend to need jumbo financing?

Higher-priced pockets such as Arcadia, Biltmore and parts of North Central can exceed conforming loan limits. Limits change each year, so we confirm the current number when you start looking.

Are there assumable mortgages in Phoenix?

Yes, particularly FHA and VA loans in newer or recently purchased homes. Assumptions are subject to servicer approval and buyer qualification, and they often take longer than a standard purchase.

How do I compare Phoenix to the East Valley?

It mostly comes down to commute, housing age and budget. Phoenix offers more historic and urban options, while the East Valley leans newer and master-planned. I can help you compare the financing for specific homes on either side.

Get started

Buying in Phoenix? Let’s run your numbers.

New loan or assumption? I’ll show you both, side by side, before you make an offer.

Typical reply: same business day · NMLS #2735366