Northeast Valley · Maricopa County

Paradise Valley mortgage broker & loan officer

Quiet streets, mountain views and careful financing.

County
Maricopa
Housing mix
Custom estates on large lots
Common loans
Jumbo · Conventional
Assumable inventory
Rare at these price points
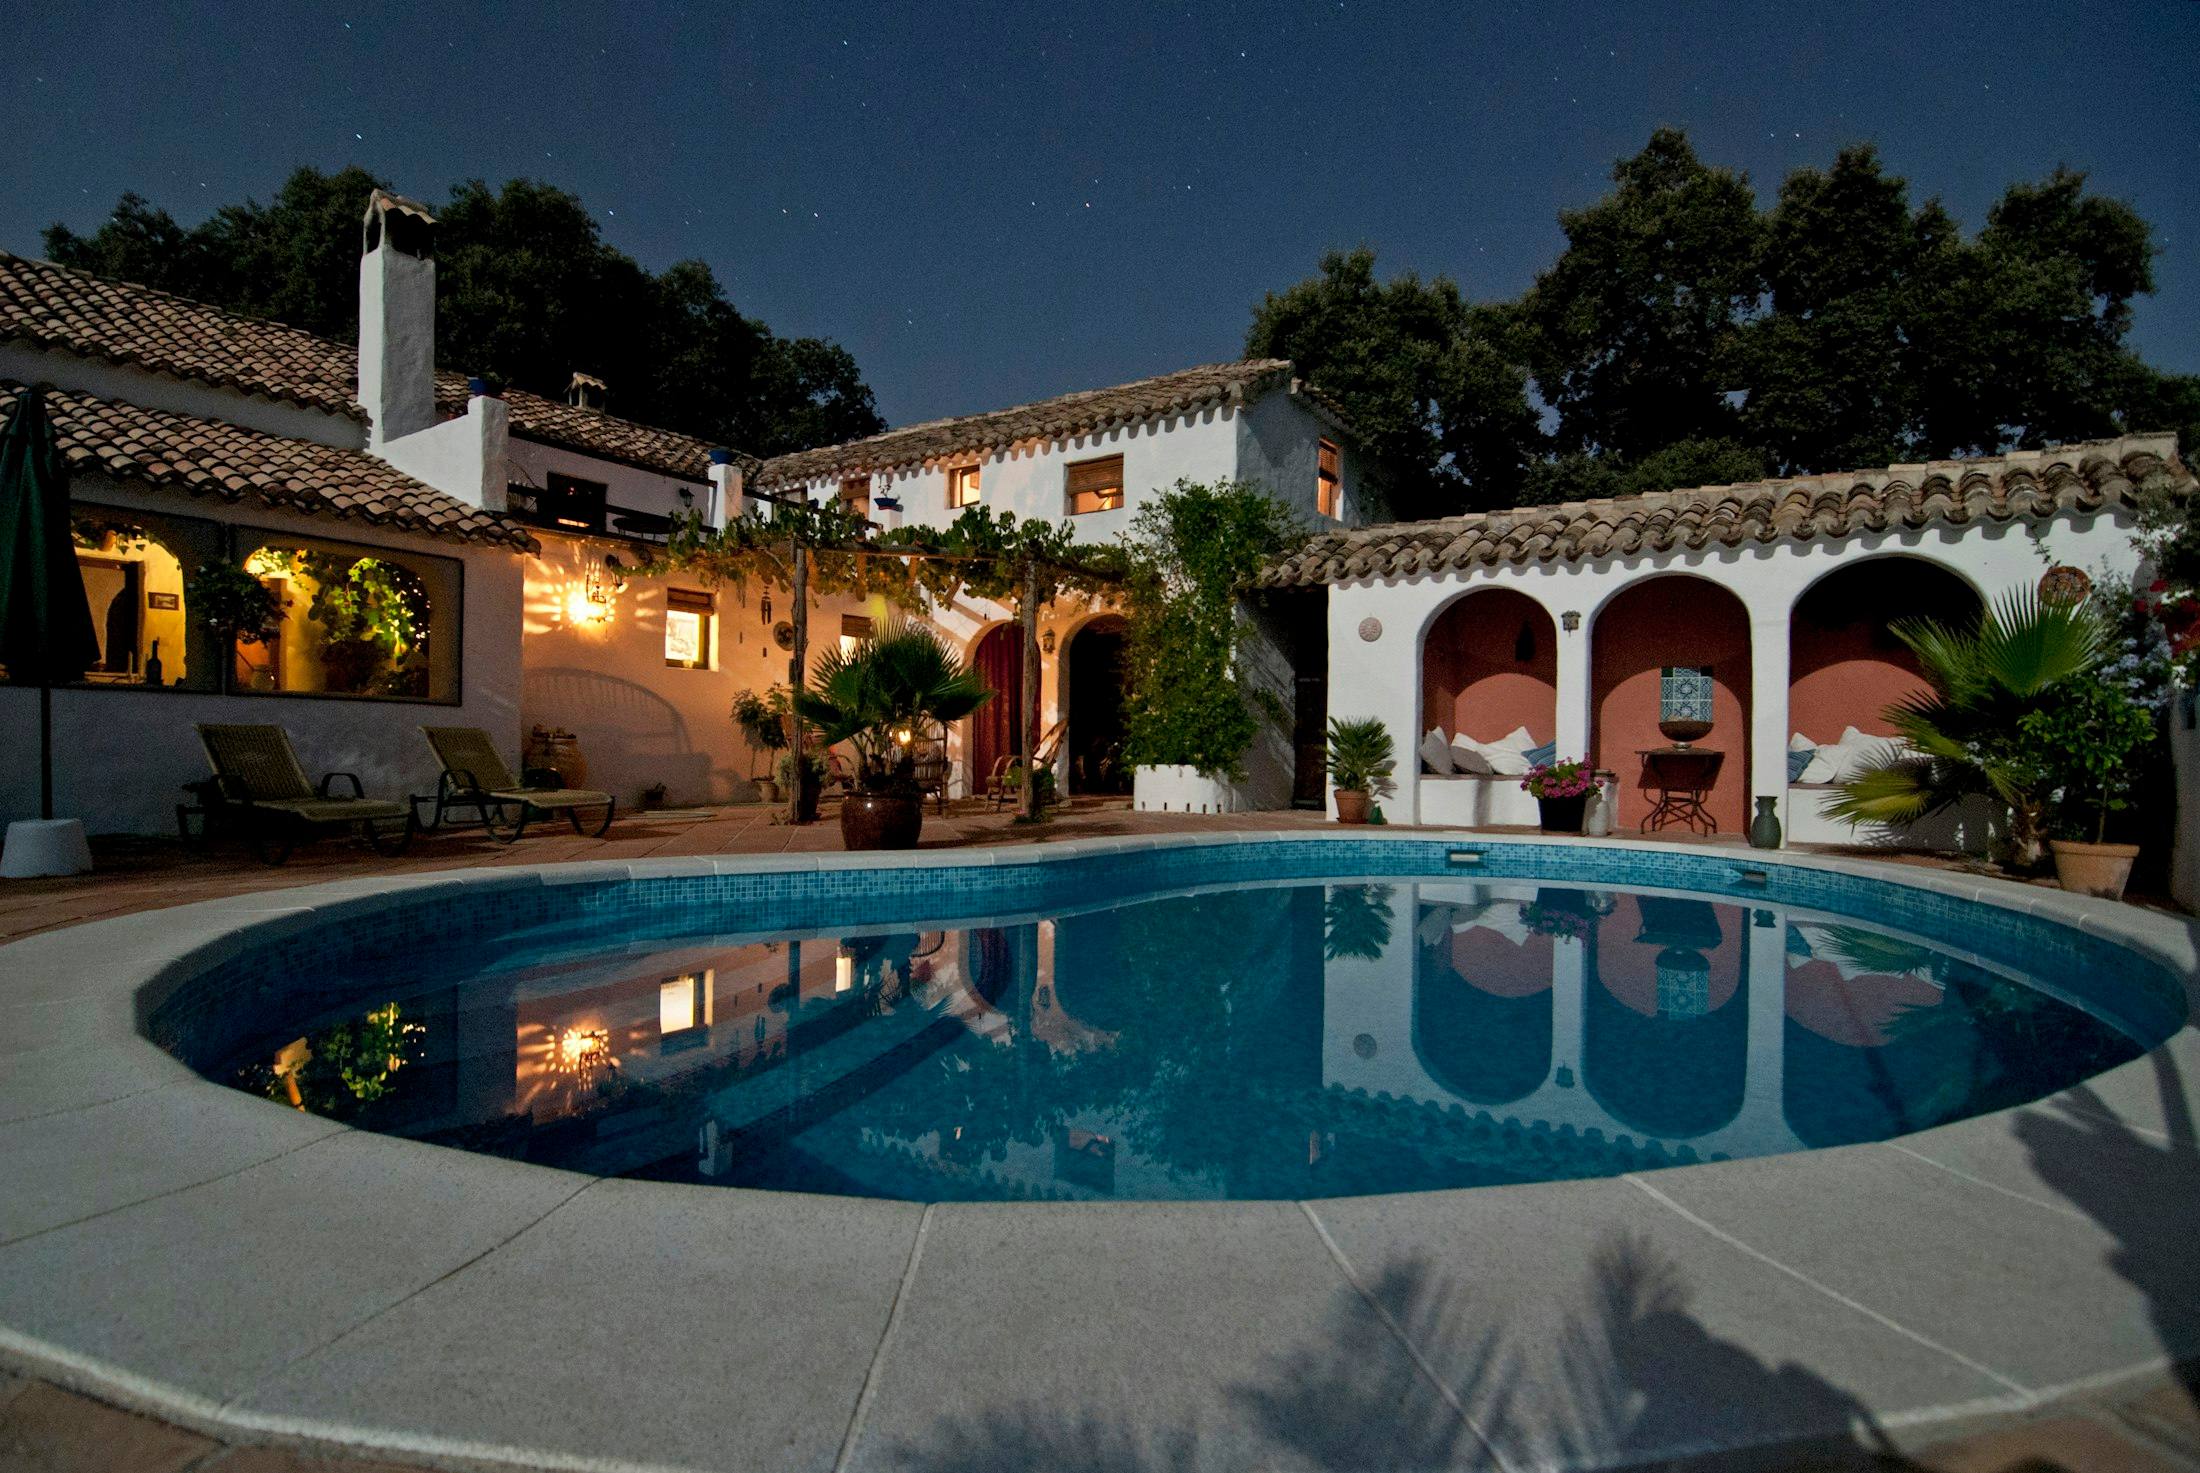
Spanish-style estate with a lit pool at night in Paradise Valley

Buying in Paradise Valley

Paradise Valley is a small, primarily residential town tucked between Phoenix and Scottsdale, framed by Camelback Mountain and Mummy Mountain. Homes sit on large lots, and many are custom estates. Financing here usually means jumbo loans, complex income and a preference for discreet, well-organized service.

Local housing context

What shapes financing in Paradise Valley

01

Large lots and custom homes

Paradise Valley is known for low-density zoning and homes on generous lots. Many properties are custom built or extensively renovated, which can make appraisals more nuanced because comparable sales are limited. An experienced appraiser and good documentation of improvements help.
02

Complex income and assets

Many Paradise Valley buyers are business owners, executives or investors whose income does not fit a simple W-2 picture. Lenders may consider tax returns, business financials, bank statements or asset-based qualifying, depending on the program. Requirements vary, so we choose the path that fits your situation.

03

Privacy and discretion

Buyers here often value a quiet, low-profile process. I keep communication direct, limit document requests to what is needed and coordinate closely with your CPA, attorney or financial advisor.

Neighborhoods

Areas I often finance

Every neighborhood carries its own mix of property types, HOAs and price points, and each one changes the right loan structure.

  • Camelback Mountain foothills

    Hillside estates where views, slope and custom construction can make appraisals more involved.

  • Mummy Mountain

    Prestigious hillside homes where jumbo financing and strong reserves are the norm.

  • Clearwater Hills & northern Paradise Valley

    Large custom homes where asset documentation often matters as much as income.

  • Central Paradise Valley flatlands

    Acre-plus lots and ranch-style or rebuilt homes, sometimes purchased as teardowns.

Assumable mortgages · Paradise Valley

Could you take over a seller’s lower rate?

Assumable FHA and VA loans are rare here because balances are usually small relative to price, leaving a very large equity gap. When one does appear, it is subject to servicer approval and buyer qualification.

FHA, VA and USDA loans may be assumable with servicer and agency approval. Buyers must qualify, and the equity gap between price and loan balance generally must be covered with cash or permitted secondary financing.

Local notes from Patrick

A quieter process

Many of my Paradise Valley clients prefer fewer calls and clearer checklists. I set expectations up front, tell you exactly which documents are needed and why, and coordinate with your advisors so you are not repeating yourself.

Income that doesn’t fit a box

Business owners, partners and investors often have strong finances that look complicated on paper. I review returns, K-1s and asset statements before we talk about rates, then match you with a jumbo structure that fits. Timing of distributions and reserves can make a real difference.

Thinking beyond the purchase

Some Paradise Valley buyers purchase with cash and then consider financing afterward, or plan a refinance once a renovation is complete. If that is on your mind, let’s discuss it before closing so the sequencing works. If you would like to start privately, a short call through my contact page is the easiest first step, and nothing needs to be submitted until you are ready.

FAQ

Paradise Valley mortgage questions

What kind of loan do most Paradise Valley buyers use?

Most use jumbo financing because prices often exceed conforming limits. Some buyers pay cash and finance later, depending on their goals.

I'm self-employed with complex income. Can I qualify?

Often, yes. Depending on the program, lenders may use tax returns, business financials, bank statements or assets; I help pick the approach that fits your documentation.

Can I buy a teardown or plan a rebuild in Paradise Valley?

Financing a lot or teardown is different from financing a finished home, and options vary by lender. Let's discuss your plan early so the structure fits.

Are appraisals harder for custom homes?

They can be, because comparable sales are limited. Documenting upgrades and working with experienced appraisers helps support value.

Get started

Buying in Paradise Valley? Let’s run your numbers.

New loan or assumption? I’ll show you both, side by side, before you make an offer.

Typical reply: same business day · NMLS #2735366